
Before jumping into this issue of the First Choice Federal Credit Union newsletter, we wanted to thank our staff and our membership for their patience, understanding and kindness over the last few weeks. You are all amazing, and by working together, we weathered a difficult storm.
Can I Buy It? vs. Can I Afford It?
A word from our CEO
We live in a consumer-driven society.
We are constantly bombarded with images of success, wealth, and possessions delivered directly to the devices in our hands.
You could say this is a new phenomenon, but I know better. Back in the 1990s, I got my first apartment. I was receiving my first real paychecks and quickly discovered a new talent at which I was remarkably gifted… spending money.
We hear an awful lot about “keeping up with the Joneses,” but do you know who I was trying to keep up with? My parents.
Until then, I had enjoyed a comfortable existence. My room was well furnished, the refrigerator was full, and my sheets were just the right thread count. Then I moved out and discovered that all those comforts were rather expensive.
Eventually, someone gave me some wise perspective: It had taken my parents years to build the life I was accustomed to enjoying.
I was trying, in a few short months, to match what had taken them years to achieve.
A pantry so well stocked that Giant Eagle might call my mother for supplies —and a big-screen television—were not my birthright. They were the results of hard work, careful choices, and years of saving.
I had to learn an important lesson:
“Can I buy it?”
is not the same question as
“Can I afford it?”
Approval for a loan or credit card may answer whether someone qualifies to obtain something. Affordability asks a harder question: Does this payment still leave enough room to live, save, meet other obligations, and handle the unexpected?
At First Choice, we approve and process loans all day long… in fact, we are pretty good at it. We are eager to help our members make a purchase, complete a repair, consolidate debt, or accomplish an important goal.
Yet there are also times when we must decline a request. Even when a loan is approved, we may discuss whether the payment comfortably fits within the member’s overall financial plan.
We are not here to judge members’ spending choices. However, we do have a responsibility to ask thoughtful questions and help members consider the long-term effects of their decisions.
We are not here merely to grant one loan. We want to build relationships that last through a lifetime of financial decisions. That means caring not only about what our members want today, but also about the future they are working to build.
It is tempting, as Burger King has told us, to “have it your way.” But sometimes the wisest choice is to pause and ask: I may be able to buy it – but can I truly afford it?
ATTENTION Legacy Family 1st Credit Card Members
The final step in bringing our two credit unions together is the conversion of our credit card programs. Here is the good news: The programs have operated almost identically from the beginning. All the features and benefits you have come to know and expect will remain available with your new card—even the card’s appearance!
Legacy Family 1st members should receive a new First Choice credit card in the mail by the first week of November. Your existing card will continue to work through December 2, 2026.
There are only three significant changes:
- Your new card will have a different account number, security code (and potentially expiration date)
- Your monthly payment due date will change from the 10th to the 21st of each month
- You will now be able to link your credit card to our mobile app!
- Reduce the number of payments you make each month
- Replace high or variable interest rates with a more manageable rate
- Establish a clear schedule for paying off your debt
- Free up room within your monthly budget
Your first statement will include an extended grace period. This will ensure that members who normally pay their balances in full do not incur interest on new purchases because of the transition.
Your interest rate, credit line, minimum payment calculation, fees, and all other account terms will remain the same.
You should have already received additional information in the mail regarding this conversion, but we wanted to reinforce the message and make sure you are prepared for the change.
Thank you for your continued business and for making First Choice your choice for banking!
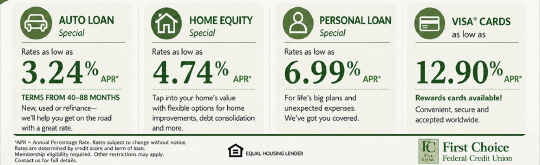
Our Rates
An Update About Your ATM Card
Over the years, many members have opened checking accounts and moved from an ATM card to a debit card. An ATM card provides access to your savings account at an ATM. A debit card provides access to both savings and checking at an ATM and can also be used to make purchases.
Our existing ATM cards do not have expiration dates. In late 2026 and early 2027, we will begin replacing them with new cards that include an expiration date.
If you have used your ATM card within the past 12 months, you will automatically receive a replacement in the mail.
To help protect your account and avoid the expense of replacing unused cards, inactive ATM cards will be closed unless you request a replacement.
If you would like to keep an ATM card—even as a backup way to access your savings—please contact our office. We will be happy to arrange a replacement.
Once the card replacement process is complete, existing ATM cards will no longer work. If you need an ATM card in the future, you can request one at any time.
A Clear Path Forward
Credit cards. Personal loans. Medical expenses. Store accounts.
Individually, each payment may appear manageable. But when several payments arrive throughout the month… each with a different due date, interest rate, and minimum amount… they can quickly become difficult to manage.
If that sounds familiar, it may be time to consider debt consolidation.
A consolidation loan from First Choice may allow you to combine several existing balances into one loan with one monthly payment. Depending on your current debts and the terms for which you qualify, consolidation could help you:
Debt consolidation does not make what you owedisappear, but it can provide something nearly as valuable… a clear path forward.
The right consolidation plan is about more than obtaining a new loan. It begins with reviewing what you currently owe, the interest rates you are paying, and what payment realistically fits within your budget. Our lending staff can help you examine those numbers and determine whether consolidation makes sense for you.
At First Choice, you are more than an application or a credit score. We understand that financial circumstances can change. Unexpected repairs occur, medical expenses arise, and sometimes balances simply accumulate faster than we intended.
There is no judgment and no lecture, but we will have a conversation about where you are today and where you would like to be tomorrow.
Our advice takes into account your personal well-being too. We do not encourage people to take a vehicle loan that has 5 years left and roll it into a new 15-year Home Equity Loan. That might lower your monthly payment, but it could leave you paying for the vehicle beyond its useful life. However, we can take a look at your current rate and term and make the best possible recommendation for you. We want to ensure the plan is not only affordable, but also practical and beneficial.
If multiple payments are making your financial life more complicated than it needs to be, talk with one of our lending professionals. We may be able to help you replace several monthly obligations with one payment and one plan.
More Than An App
There was a time when nearly every financial transaction required a trip to the financial institution. Today, members can check a balance, deposit a check, transfer money, pay a bill, or apply for a loan without ever leaving home.
That convenience is valuable and it is something our members have every right to expect. At First Choice, we continue to invest in technology that will make banking faster, easier, and more accessible. We want members to be able to manage their finances when and where it is convenient for them.
However, a credit union must be more than an app. An app can display your account balance, but not hear the concern in someone’s voice. It can accept a loan application, but not know the story behind the score. It can process a transaction, but it may not recognize when a member is confused, frightened, or simply needs someone to take the time to explain what comes next.
Some financial needs are routine. Others are deeply personal. A first car, an unexpected repair, a job loss, a divorce, or the death of a loved one cannot always be reduced to a series of buttons on a screen. In those moments, people may need patience, judgment, flexibility, and a real conversation. That is where personal service still matters.
Technology is at its best when it handles routine tasks efficiently and gives our staff more time to help members with the complicated ones. It should provide more choices—not remove the choice of speaking with someone who knows our community and cares about the outcome.
As financial services become increasingly digital, First Choice will continue to move forward. We know that our members expect modern technology, greater convenience, and access beyond normal business hours. We intend to provide those things. But we also know that progress should not require us to abandon what makes a credit union different.
First Choice was built on relationships. We live in the communities we serve. Our members are not merely account numbers, applications, or transactions. They are our neighbors, friends, families, and local businesses.
Sometimes you need the convenience of an app.
Sometimes you need a person who will listen.
At First Choice, we believe you should have both.